

This summer, students from the University of Delaware’s Alfred Lerner College of Business and Economics discovered new avenues for professional preparation and practical hands-on experience. Lerner College students pursued an array of internships, externships and other professional development opportunities. From MBA scholars to undergraduates entering their second year at UD, students across a spectrum of Lerner programs shared their experiences accomplishing an assortment of projects.
Our “My Summer Internship” series highlights these unique experiences, showcasing how students translated classroom knowledge into real-world success.
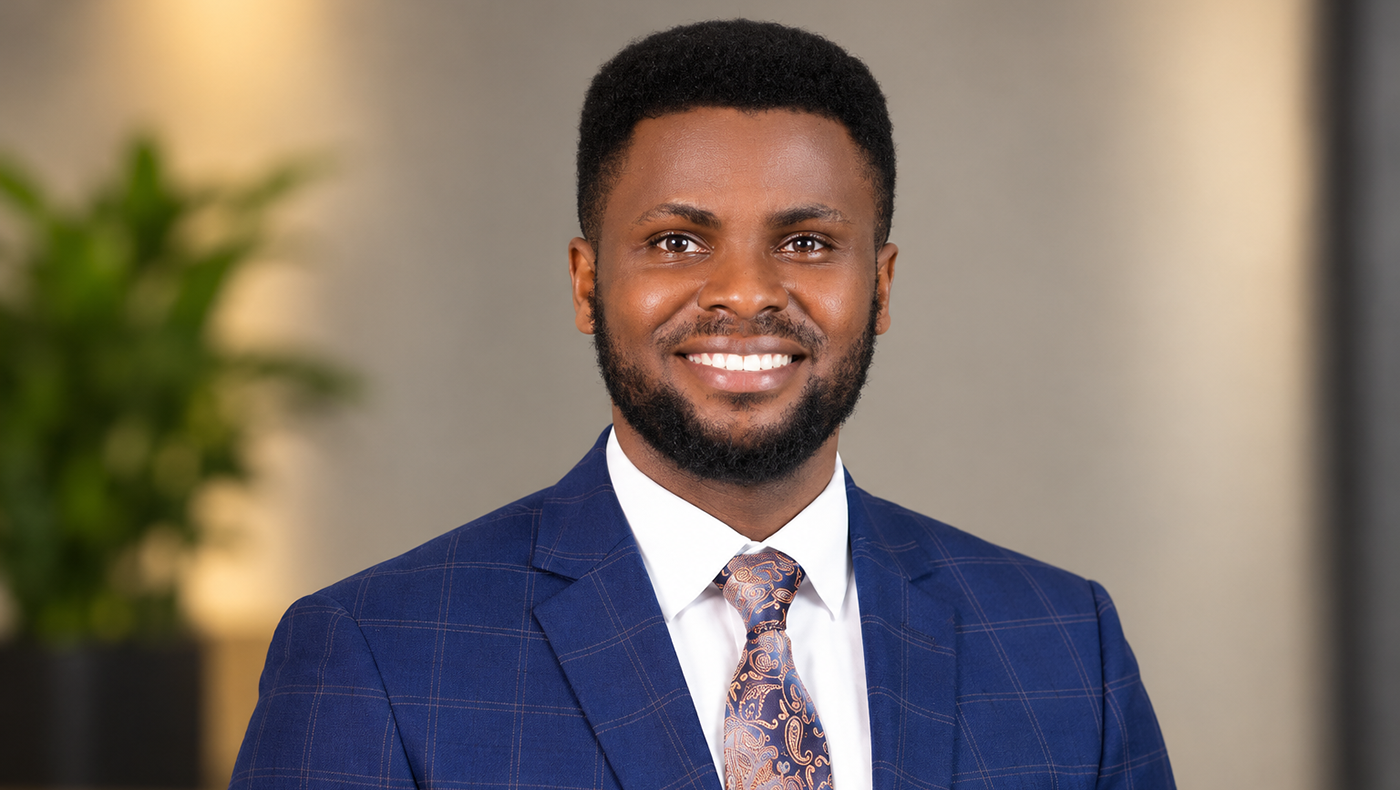
Tunmbi Okediran, Class of 2028, financial services analytics Ph.D. student, spent his summer as a graduate associate at Barclays.
Lerner: How did you find out about this internship? Why did you pursue it?
Okediran: I found out about this internship through the Lerner Graduate Internship Program. I pursued it because Risk Weighted Assets sits close to my own PhD research on financial risk and asset pricing, and it’s a niche within banking I found genuinely interesting rather than just a resume line. The chance to see how capital regulation actually plays out inside a real institution was a big draw.
Lerner: What was the most exciting task or project that you completed?
Okediran: One of the most rewarding parts of my internship was investigating why a specific default category was carrying a disproportionately high capital requirement. Digging into the model, I found it was systematically over-penalizing that category relative to its actual risk, and I was able to flag it as a real opportunity for capital optimization. It was exciting to see a research-style investigation lead to something the team could actually act on.
Lerner: What did you learn from the internship that you think you wouldn’t have learned elsewhere?
Okediran: The internship gave me a much deeper, systems-level understanding of how risk-weighted assets actually behave across different portfolios, how the same underlying model inputs can produce very different capital outcomes depending on portfolio composition and borrower characteristics. That kind of intuition is hard to build from coursework or academic papers alone; it really only comes from sitting inside the data and watching how a live regulatory capital model responds to real-world variation.
Lerner: What is an example of a time where you were able to apply what you’ve learned at Lerner to your role?
Okediran: My coursework in Financial Services Risk Analytics and Statistical Learning gave me a strong foundation in the kind of regression and statistical reasoning I used daily to investigate capital model behavior at Barclays. Being able to move from a classroom framework straight into diagnosing real discrepancies in a live regulatory capital model made the coursework feel immediately useful rather than abstract.
Lerner: Did you face any challenges during your internship? If so, what was the issue and how did you overcome it?
Okediran: The biggest initial challenge was simply ramping up on the scale and complexity of a large bank’s data and regulatory capital framework quickly enough to contribute meaningfully. I got past it by leaning heavily on my team for context early on and treating the first few weeks as a deliberate learning phase before trying to move fast on any one investigation.
Lerner: What are your career plans, and how do you think the internship will push you closer to your professional goals?
Okediran: I’m working toward a career in quantitative research within financial services, ideally in a role that combines rigorous statistical/ML modeling with real market or risk problems. This internship gave me a much clearer picture of how that research translates into a live banking environment, which has sharpened exactly what I’m looking for as I apply to quantitative research roles for after my PhD.